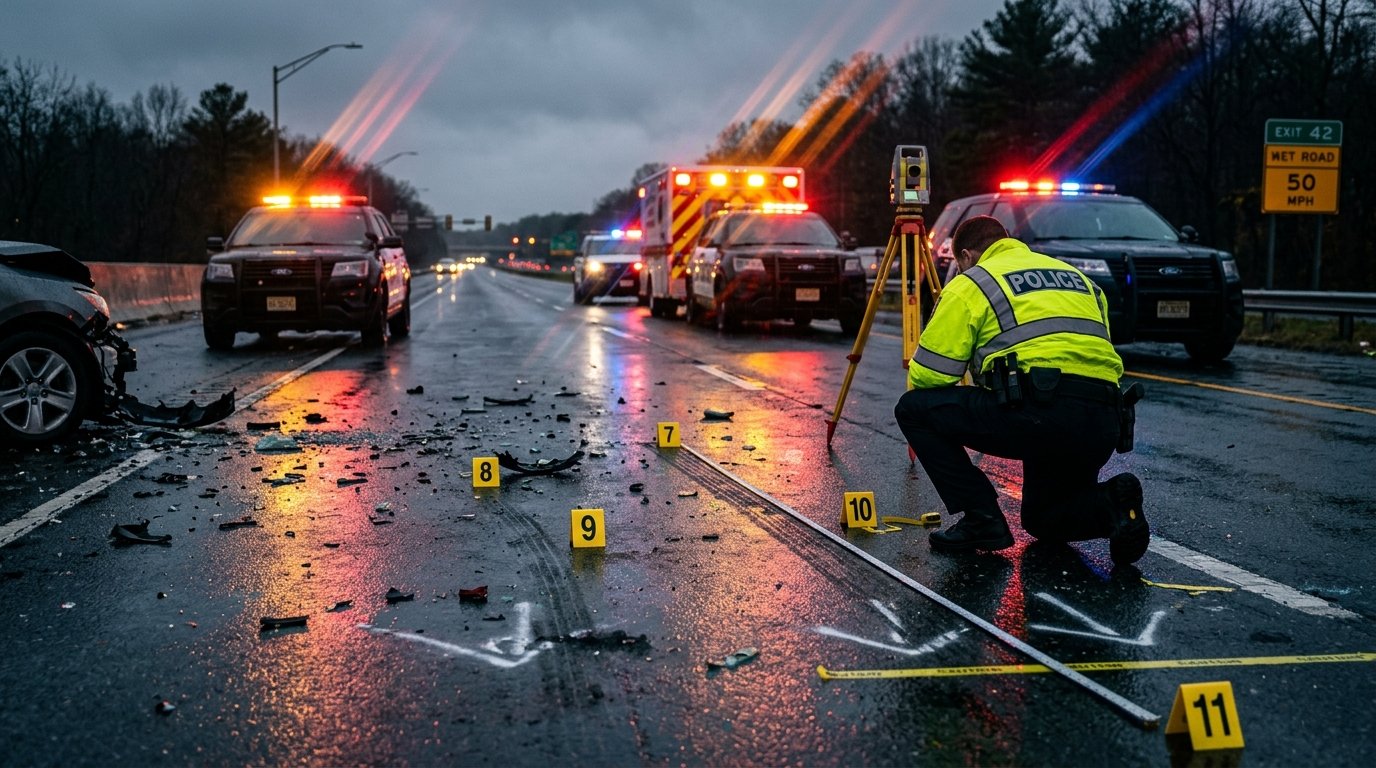
The First 72 Hours Determine the Outcome of Your Claim
The actions you take immediately following a motor vehicle collision will dictate whether an insurance defense carrier accepts full liability or succeeds in minimizing your financial recovery. Insurance adjusters are trained to interpret any procedural hesitation—such as delayed medical attention or casual conversation at the accident scene—as evidence that your injuries are minor or unrelated to the collision.
Crucial 72-Hour Checklist
- Seek immediate Level-1 or urgent trauma evaluation: Even if symptoms feel minor, adrenaline masks severe cervical spine, disc herniation, and traumatic brain injury symptoms.
- Secure the official police crash report number: Request the investigating officer’s name, badge number, and agency report reference before departing.
- Photograph all 360-degree environmental evidence: Skid mark lengths, vehicle rest angles, traffic light phasing, and road debris are critical for forensic crash reconstruction.
- Decline recorded statements: You have no legal obligation to give a recorded interview to the opposing motorist’s insurance adjuster before retaining counsel.
Step 1: On-Scene Evidence Preservation
If physical condition permits, document everything before tow trucks clear the scene. Modern vehicle electronic data recorders (EDRs) capture telemetry such as vehicle velocity, brake engagement, and steering angles, but physical physical road marks fade rapidly under traffic and weather conditions.
Ensure you capture wide-angle context shots establishing sightline obstructions, construction warnings, and weather conditions, as well as close-ups of all vehicle impacts, tire tread conditions, and deployed airbags.
Step 2: The Medical Treatment Gap Danger
One of the most devastating weapons in an insurance carrier’s defense arsenal is the so-called "treatment gap." If an accident occurs on Monday and the victim does not seek medical care until Friday, defense counsel will inevitably argue that intervening daily activities—not the crash—caused the injuries.
| Time Elapsed | Medical Action | Insurance Defense Implication |
|---|---|---|
| 0 - 24 Hours | Emergency room or trauma center diagnostic evaluation | Establishes direct causation between crash kinetics and injury. |
| 24 - 72 Hours | Follow-up with orthopedic specialist or neurologist | Documents progressive symptom onset before initial settlement offers. |
| Beyond 72 Hours | Delayed initial clinical visit | Carrier argues "gap in care" and alleges pre-existing conditions. |
Step 3: Managing Insurance Carrier Contact
Within 24 to 48 hours, the at-fault driver’s insurance adjuster will call under the guise of "checking on your wellbeing." In reality, adjusters are incentivized to secure admissions of comparative fault, elicit recorded statements before the full scope of orthopedic trauma is diagnosed, or offer an immediate $1,500 check in exchange for signing a blanket global liability release.
Politely inform the adjuster that you are undergoing diagnostic medical evaluations and that all communications regarding liability and damages must go through your legal representative.